Tax, Artificial intelligence, Technology
Tax technology is ready, but the operating model has work to do
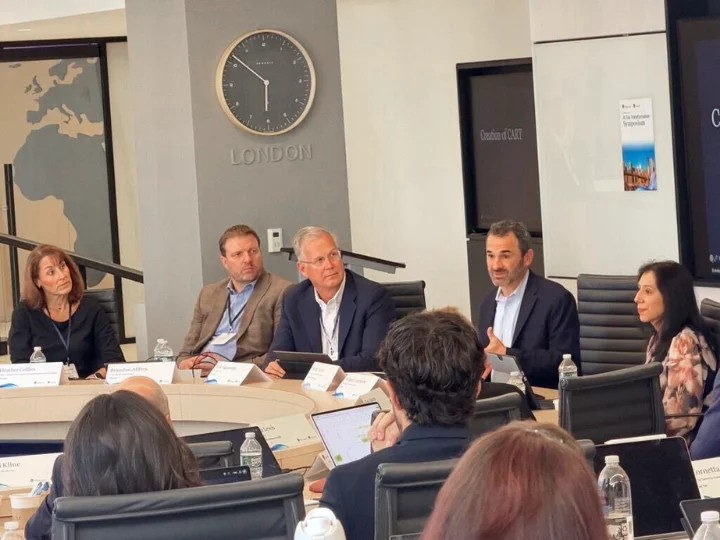
Tax preparation is approaching zero effort, and review is next. That was the working premise at the inaugural CPA.com AI Tax Transformation Symposium, where CPA.com and the AICPA brought together 100 firm and technology leaders to share knowledge and perspectives into how artificial intelligence (AI) is changing tax.
What we heard maps to the five drivers of CPA.com's tax transformation framework. The technology works. The operating model around it is what holds firms back.
Here are the top takeaways.
Strategy and governance: Transformation ownership beats announcements
The framework starts with two questions: What are we building and why? Many firms skip that first step and go straight to tools. Pressure to show AI progress is coming from investors and competitors alike, and fear of missing out has become pervasive. Too many firms respond by announcing AI initiatives before they have a plan to deliver them, but an announcement is not a strategy. They need an aligned understanding of what they’re trying to achieve and specific outcomes and KPIs they plan to deliver.
Even with a defined strategy, many firms stall in the execution without strong governance in place. When partners pick their own tools, they end up with different data, duplicate spend, security gaps, and review layers that protect quality but slow every decision. But nobody owns the risk. Our framework points to a different model: leading firms treat the tax practice as a business unit with its own strategy and formal accountability for transformation outcomes.
Firm takeaway: Assign clear ownership for transformation outcomes, with the authority to decide and take responsibility for the risk.
Talent and advisory culture: Judgment is the gap
In the old apprenticeship model, junior staff built judgment through years of preparing returns. But AI is closing that path. The risk is that AI sounds just as confident when it is wrong as when it is right. The example is simple, but the lesson is not: Working with AI makes professional skepticism even more important, and junior staff still need repetitions for building that judgment.
Firms are answering with simple fixes to help earlier career staff build judgment in different ways. Have them explain a return instead of handing it off, ask what they think before giving the answer, run client simulations, and add teaching to manager scorecards.
Firm takeaway: Define the technical and advisory skills your practice requires, then build new training models to accelerate your team’s development.
Technology and AI integration: Capacity only counts if you use it
AI is already creating capacity at scale. Many firms are finding success in automating tax returns with better accuracy, even reaching 100% on some complicated returns. One firm shared they are moving toward 90% of their returns being fully automated now. But capacity only counts when firms put it to work, and new opportunities are surfacing for those that integrate AI into their review and advisory processes.
Building capacity for advisory opportunities can be accelerated through using client data appropriately. Because vendors build on the same underlying models, a firm’s competitive advantage comes from its own data and documentation. Firms face a policy decision for how much data AI agents can access through emails, transcripts, workpapers, and returns to identify advisory discussions with clients.
Utilizing AI for client service capacity can only move as fast as users trust the output. As models and tools continue to improve, firms should do their homework for reliability, applicability, and security — choosing the tools that are vetted and provide additional value to firm operations and clients. Danny Werfel, J.D., former IRS Commissioner and author of the AI Risk Framework for Tax, which the AICPA’s Council on AI Risk in Tax (CART) is now refining, summed up his advice at the symposium in three words: “slow your roll.”
Firm takeaway: Before rolling out the next tool, set a goal for the freed hours, such as more advisory work or more returns per person.
Service and business model: Hourly billing penalizes efficiency
Since firms still bill primarily by the hour, AI’s ability to drastically reduce the time it takes to produce the same work creates a pricing problem. As firms also shift toward deeper advisory services, they have to think differently about how they price for the value they provide.
One firm at the symposium shared how they’re facing 70,000 engagement letters for January with no standard answer on price. Another highlighted how they moved to about 90% fixed fee and dropped staff billable-hour goals, because people will not adopt a tool that lowers their own number.
No single pricing model fits every engagement, and firms are experimenting with fixed fee, value-based pricing, subscriptions, and tiered packages. Whatever the model, the goal is the same: Price for the value the client receives, with the firm’s cost to deliver as the floor. That shift pays off. Firms that went all in on pricing advisory service for value reported higher revenue per client even with fewer clients.
Firm takeaway: Take a firmwide, strategic approach to pricing, with a clear policy for how the firm prices for value instead of deciding engagement by engagement.
Operational excellence: Execution decides the outcome
Most transformations fail in execution, not strategy. McKinsey research puts the failure rate of large-scale transformation efforts at about 70%. Symposium participants described how that happens in tax: Firms bolt tools onto legacy workflows and expect results. Vendors warn that firms cannot automate processes they have not documented.
It may take significant onboarding time for AI-enabled tools to access data and redesign workflows to successfully achieve expected outcomes. The process of rolling out new tools needs to be rethought. Moving too fast or too slowly can derail the best laid plans.
One firm rolled out new tools too quickly for their team to adopt and learn, even though the tools passed every test the firm had required. Another firm, waiting for a perfect solution, found their evaluation and diligence processes too long and complicated. They changed their process to 30-day evaluation sprints with a dedicated team for new tools to determine pilot-ready solutions. That team stages the rollout, measures capacity impact, plans training for effective tool usage, and redesigns processes for advisory opportunities.
Firm takeaway: Document your firm’s tax processes and workflows before automating with technology and AI tools.
What comes next
The coming busy season will be the first with AI at scale and the real test of these ideas, so firms should plan their debriefs now. We’ll be sharing more insights into where firms stand on these same issues in the upcoming CPA.com’s State of Tax Transformation survey report, which will be released at the DCPA Conference in December. Sign up to be notified as soon as the report is live.
Learn more about the CPA.com tax transformation framework.